The price on a metal souvenir invoice is not the number that ends up on the customs declaration. Under the valuation rules that most importing countries share, the dutiable value starts from the price actually paid or payable and then adds specific items that the buyer supplies or causes to be supplied outside the invoice, most often a die casting mold, sometimes artwork, sometimes packing materials, sometimes a royalty tied to the sale. For a buyer importing custom metal souvenirs that gap is not an edge case, it is the normal case, because custom orders almost always involve buyer-funded tooling. Getting the valuation file right before the container is booked is the difference between a predictable landed cost and a demand for duty from Customs months later.
Why the Invoice Price Is Not the Dutiable Value
Start with the definition the whole system hangs on. Under 19 CFR 152.102, the “price actually paid or payable” is the total payment, whether direct or indirect, that is made or to be made for imported merchandise by the buyer to or for the benefit of the seller. Two exclusions are written into that definition. Charges, costs and expenses for transportation, insurance and related services incident to the international shipment of the merchandise from the country of exportation to the place of importation in the United States sit outside the price. And the word “payable” is deliberately broader than “paid”: it refers to a situation in which the price has been agreed upon but actual payment has not been made at the time of importation.
The regulation on transaction value, 19 CFR 152.103, makes the same point in operational terms. The price is considered without regard to its method of derivation. It may be the result of discounts, increases or negotiations, or it may be arrived at by applying a formula. And here is the sentence that matters most to buyers who finance shipments through a bank: payment may be made by letters of credit or negotiable instruments, and may be made directly or indirectly.
Indirect payment is the quiet one. It includes the buyer settling, in whole or in part, a debt owed by the seller, or the buyer receiving a price reduction on the current importation as a means of settling a debt owed to him by the seller. The regulation’s own example is worth reading closely. A United States company pays $2,000 to a foreign toy factory for a shipment. Of that, $1,850 covers the toys and $150 covers ocean freight and insurance. The factory would have charged $2,200 for the toys, but because it owed the buyer $350 it charged $1,850. The transaction value is $2,200, the sum of the $1,850 paid and the $350 set-off, and the $150 of freight and insurance is excluded. Set-off against tooling invoices, against a development fee, or against a previous order is the same mechanism. A buyer who nets a $2,000 mold charge against a $2,000 invoice has not saved $2,000 of dutiable value.
Rebates run the other way. Any rebate of, or other decrease in, the price actually paid or payable made between the buyer and seller after the date of importation is disregarded in determining the transaction value. A discount agreed after the goods have arrived does not lower the declared value, which means a retrospective rebate negotiated by a buyer should not be assumed to reduce the duty already assessed.
Transaction value is only available if a set of conditions is met. There must be no restrictions on the disposition or use of the merchandise by the buyer other than restrictions imposed or required by law, restrictions limiting the geographical area in which the goods may be resold, or restrictions that do not affect substantially the value of the goods. The sale or price must not be subject to any condition or consideration for which a value cannot be determined. No part of the proceeds of any subsequent resale, disposal or use of the merchandise may accrue to the seller, unless an appropriate adjustment can be made. And the buyer and seller must not be related, or the transaction value must be shown to be acceptable even though they are.
Two of those conditions are directly relevant to how metal gift orders are usually contracted. The restriction test is why a buyer who signs a purchase agreement containing resale pricing or territory restrictions needs to look closely at the wording. The condition test is why a clause that ties the price to the eventual resale price of the souvenir in the destination market is a problem rather than a commercial convenience, because the value of that condition cannot be determined. Where the price depends on the price at which the buyer sells other merchandise back to the seller, transaction value is unavailable for the same reason.
Whether freight is inside the price depends on the terms of sale, which is why the classification and delivery terms discussed in our guide to importing metal souvenirs with HS codes and Incoterms matter for valuation and not only for classification. If the price does not include a charge for foreign inland freight, that charge is not added to the price. Where the price does include a foreign inland freight charge, whether itemised separately on the invoice or not, that charge is generally part of the transaction value to the extent included in the price. Charges may be treated as incident to the international shipment if they are identified separately and occur after the merchandise has been sold for export to the United States and placed with a carrier for through shipment to the United States. Evidence of that arrangement is established by a through bill of lading presented to Customs, either at the port of entry or electronically.
What Counts as an Assist, and What Does Not
An assist is the mechanism that most often separates a metal souvenir invoice from its declared value. The definition in 19 CFR 152.102 covers any of the following, supplied directly or indirectly, and free of charge or at reduced cost, by the buyer of imported merchandise for use in connection with the production or the sale for export to the merchandise.
The four categories are worth reading as a checklist, because a custom metal gift order touches several of them at once:
- Materials, components, parts and similar items incorporated in the imported merchandise.
- Tools, dies, molds and similar items used in the production of the imported merchandise.
- Merchandise consumed in the production of the imported merchandise.
- Engineering, development, artwork, design work, and plans and sketches that are undertaken elsewhere than in the United States and are necessary for the production of the imported merchandise.
The second category is the one that dominates metal gift sourcing. A die casting mold for a custom souvenir is a tool used in the production of the imported merchandise. When a brand funds that mold, or funds it at a reduced rate, the mold is an assist by definition. The same logic applies to a stamping die for a stainless steel medallion, a fixture for a machined component and the gauge used to check a critical dimension.
The fourth category is the one most brand teams get wrong in both directions. Design work undertaken outside the United States that is necessary for production is an assist. Design work undertaken inside the United States is not. There is a narrow exception and it is worth understanding, because it is where agency design support usually sits: no service or work covered by the design category is treated as an assist if the service or work is performed by an individual domiciled within the United States, is performed by that individual while acting as an employee or agent of the buyer, and is incidental to other engineering, development, artwork, design work or plans and sketches undertaken within the United States.
Three further rules fix the value of a design-related assist. Where the assist is available in the public domain, its value is the cost of obtaining copies. Where the production of an assist occurred in the United States and in one or more foreign countries, the value is the value added outside the United States. And where the assist was purchased or leased by the buyer from an unrelated person, the value is the cost of the purchase or of the lease.
Packing costs carry their own definition. They are the cost of all containers, exclusive of instruments of international traffic, and coverings of whatever nature, and of packing, whether for labour or materials, used in placing merchandise in condition packed ready for shipment to the United States. The exclusion for instruments of international traffic matters more than it sounds: a shipping container is not a packing cost, but the foam insert, the printed inner box and the master carton are. Our notes on export packaging compliance for metal souvenirs cover the wood treatment requirements that apply to the same packaging that carries this cost.
The Five Additions That Change the Number You Declare
19 CFR 152.103 sets out the transaction value as the price actually paid or payable for the merchandise when sold for exportation to the United States, plus amounts equal to five things. The wording is exact and the list is closed.
| Addition under 19 CFR 152.103(b)(1) | What it covers | Typical appearance in a metal gift order | Evidence worth keeping |
|---|---|---|---|
| (i) Packing costs | Packing costs incurred by the buyer with respect to the imported merchandise | Buyer-supplied foam inserts, printed inner cartons, branded master cartons | Packing list separating container cost from packing labour and materials |
| (ii) Selling commission | Any selling commission incurred by the buyer with respect to the imported merchandise | Commission paid to the factory’s sales agent in the country of export | Agency agreement showing the commission is a selling commission and to whom it is paid |
| (iii) Value of any assist | The value, apportioned as appropriate, of any assist | Die casting mold, artwork, gauges, customer-supplied components | Mold invoice or production cost, amortization schedule, design fee and its place of performance |
| (iv) Royalties and licence fees | Any royalty or licence fee related to the imported merchandise that the buyer must pay, directly or indirectly, as a condition of the sale for exportation to the United States | Licence fee payable as a condition of purchase, where the seller’s right to produce the design is the consideration | Licence agreement showing whether payment is a condition of the export sale and to whom it is paid |
| (v) Proceeds of subsequent resale | The proceeds of any subsequent resale, disposal or use that accrue, directly or indirectly, to the seller | Deferred payment tied to sell-through in the destination market | Sales reporting and remittance records for the units sold |
Two conditions govern whether an addition actually happens. The price is increased by the amounts attributable to those five items, and to no others, but only to the extent that each amount is not otherwise already included in the price actually paid or payable, and only if the addition is based on sufficient information. Then comes the sentence that changes how a buyer should treat a documentation gap: if sufficient information is not available, for any reason, with respect to any amount referred to in this section, the transaction value will be treated as one that cannot be determined.
Sufficient information is itself defined in 19 CFR 152.102. It means information that establishes the accuracy of any amount added, deducted or adjusted under the valuation subpart, and the extent to which those amounts are not already included in the price. In practice, this is the difference between a mold the buyer knows the cost of and a mold the buyer received free of charge with no record of what it cost to make. In the first case the addition is a number. In the second case there is no number, and without a number the whole transaction value can collapse.
Selling commission deserves one clarification, because the terms get confused in contracts. The regulation defines it as any commission paid to the seller’s agent who is related to or controlled by, or works for or on behalf of, the manufacturer or the seller. That is the arrangement that gets added. A commission paid to the buyer’s own buying agent is a different arrangement and is not the addition this provision describes. For an importer buying from a factory, the practical question is whether the factory sells through an agent in the country of export, and if so whether that agent’s commission is already embedded in the invoice price or billed separately.
Molds, Dies and the Tooling Question
The valuation of a tooling assist is set out separately, because it is the most valuable assist in this product category and the most frequently mishandled.
When an assist consists of tools, dies, molds or similar items used in the production of the imported merchandise, the value is the cost of acquisition if the buyer bought it from an unrelated seller, and the cost of production if the buyer produced it or a person related to the buyer produced it. If the assist has been used previously by the buyer, whether acquired or produced by him, the original cost of acquisition or production is adjusted downward to reflect its use before the value can be determined. If the assist was leased from an unrelated seller, the value is the cost of the lease. In every case the value includes transportation costs to the place of production. Repairs or modifications to an assist may increase its value.
The regulation’s second example is the custom souvenir case in a single line. A United States importer supplied molds free of charge to the foreign shipper, the molds were necessary to manufacture the merchandise for the importer, some were made by a company in the United States and others in a third country. Should the appraised value include the value of the molds? Yes. It is an addition required to be made to transaction value.

How that value is spread across the goods is called apportionment, and the regulation allows the importer to drive it. The apportionment of the value of assists to imported merchandise is made in a reasonable manner appropriate to the circumstances and in accordance with generally accepted accounting principles. The method accepted by Customs depends on the documentation the importer submits. If the entire anticipated production using the assist is for exportation to the United States, the total value may be apportioned over the first shipment, if the importer wishes to pay duty on the entire value at once; over the number of units produced up to the time of the first shipment; or over the entire anticipated production. An importer may also request some other method consistent with generally accepted accounting principles.
The interpretive note spells out the choice with a mould and a ten thousand unit contract. By the time the first shipment of one thousand units arrives, the producer has already made four thousand. The importer may request apportionment over one thousand units, over four thousand units, over ten thousand units, or any other figure that is in accordance with generally accepted accounting principles.
For a metal gift programme this is a live commercial decision, not a compliance formality. The same mold may produce a souvenir for two buyers, or produce several designs across a season. If the buyer funds the mold and the amortisation basis is left unstated, the producer and the importer may end up apportioning it differently, and the importer cannot correct that later without documentation that was never created. The right place to settle it is the purchase agreement, alongside the acceptance, rejection and damages terms we cover in metal souvenir purchase agreement terms, and it should also appear as a line in the request for quotation so the tooling cost is visible from the start. Our B2B RFQ template for custom metal gifts sets out the information that makes a tooling quote comparable between suppliers.
One point is easy to overlook. The cost of a mold is not the only number that matters. If the buyer supplies components, or the factory consumes buyer-supplied packaging in production, those are assists too, and they are valued and apportioned under their own rules. A buyer who thinks of the mold as the whole assist exposure is underestimating the declaration.
Royalties, Resale Proceeds and the Payments Nobody Puts on an Invoice
Royalties and licence fees are decided case by case, and the two questions the regulation asks are precise. First, was the buyer required to pay them as a condition of the sale of the merchandise for exportation to the United States? Second, to whom and under what circumstances were they paid?
The regulation gives both a default and a caution. Royalties or licence fees for patents covering processes to manufacture the imported merchandise generally will be dutiable. Royalties or licence fees paid to third parties for use, in the United States, of copyrights and trademarks related to the imported merchandise generally will be considered selling expenses of the buyer and not dutiable. And payments made by the buyer to a third party for the right to distribute or resell the imported merchandise will not be added if they are not a condition of the sale for exportation.
The example shows why the distinction turns on structure rather than labels. A United States importer pays a royalty to an unrelated third party for the right to manufacture and sell a product made in part from the imported merchandise, and the royalty is based on the selling price of the further-manufactured product in the United States. The licence fee is not a condition of the sale of the imported merchandise for export to the United States, so it is not added. The same fee, restructured as a condition of purchase from the factory, would be treated differently. Branded merchandise programmes that combine a design licence with a manufacturing agreement should read our piece on royalty and branded merchandise arrangements alongside the licence terms themselves.
Proceeds of subsequent resale are added when they accrue to the seller. The regulation’s example is a simple unit agreement: a buyer agrees to pay the seller initially $1 per unit, with an additional $1 per unit payable upon the sale of each unit in the United States. Assuming the resale price in the United States can be determined in a reasonable period of time, the transaction value of each unit is $2. If it cannot be determined in a reasonable period, the transaction value cannot be determined for want of sufficient information. That is a severe outcome, and it is worth asking a seller to convert a sell-through arrangement into a fixed price before the goods ship rather than after.
Two things are explicitly excluded. Charges for the right to reproduce the imported merchandise in the United States are not added; that right covers originals or copies of artistic or scientific works, originals or copies of models and industrial drawings, model machines and prototypes, and plant and animal species. And reasonable costs for construction, erection, assembly or maintenance of the merchandise after importation, or technical assistance provided with respect to it after importation, are excluded, as are the transportation of the merchandise after importation, the customs duties and other federal taxes currently payable on importation, and any federal excise tax on or measured by the value of the merchandise for which vendors in the United States ordinarily are liable.
When Transaction Value Cannot Be Used
Some transactions fail the conditions and the customs value has to be found another way. The fallback is deductive value, set out in 19 CFR 152.105, and it is built around the price at which the merchandise is sold in the United States.
The timing of the sale determines the price. If the merchandise concerned is sold in the condition as imported at or about the date of importation, the price is the unit price at which it is sold in the greatest aggregate quantity at or about that date. If it is sold in the condition as imported but not at or about the date of importation, the price is the unit price in the greatest aggregate quantity after the date of importation but before the close of the 90th day after that date. If it was not sold in the condition as imported, and not sold before the close of that 90th day, the price is the unit price at which the merchandise, after further processing, is sold in the greatest aggregate quantity before the 180th day after the date of importation, and this applies only if the importer so elects at the time of filing the entry summary.
That price is then reduced by commissions usually paid for sales of the same class or kind, the addition usually made for profit and general expenses, the actual costs of transportation and insurance on international shipments of the merchandise concerned, the usual costs of transportation and insurance from the place of importation to the place of delivery in the United States if those costs are not already a general expense, the customs duties and other federal taxes currently payable, and, only in the case of the further-processing price, the value added by that processing. Packing costs are added back to the extent they are not otherwise included. Any sale to a person who supplies an assist for use in connection with the production or sale for export of the merchandise concerned is disregarded entirely.
The unit price in the greatest aggregate quantity is defined by the unit price at which the merchandise concerned is sold to unrelated persons at the first commercial level after importation, or after further processing, at which the sales take place in a total volume greater than the total volume sold at any other unit price. The interpretive notes work through the arithmetic. Where a price list gives $100 for one to ten units, $95 for eleven to twenty-five units and $90 for larger volumes, and the totals sold at each price are 65, 55 and 80, the greatest number of units sold at a price is 80, so the unit price in the greatest aggregate quantity is $90. A second example: 500 units sold at $95 each in one sale and 400 units at $90 each in another, the greatest number of units sold at a particular price is 500, so the unit price is $95.
Related-party sales are handled inside the transaction value rules rather than by defaulting to deductive value. The Center director shall not disregard a transaction value solely because the buyer and seller are related. If Customs is satisfied that the relationship did not influence the price, the price is accepted. The interpretive notes give the practical test: if it can be shown that buyer and seller, although related, buy from and sell to each other as if they were not related, that demonstrates the price was not influenced. If the price was settled in a manner consistent with the normal pricing practices of the industry, or the way the seller settles prices for sales to buyers who are not related to him, the same demonstration is available. Related persons are defined broadly in 19 CFR 152.102, including any person directly or indirectly owning, controlling or holding power to vote five percent or more of the outstanding voting stock or shares of any organization.
Further processing has its own discipline. The deduction for value added is based on objective and quantifiable data relating to the cost of the work performed, with accepted industry formulas, recipes, methods of construction and other industry practices forming the basis, and reflecting amounts for spoilage, waste or scrap. If the imported merchandise loses its identity as a result of further processing, the method is unavailable unless the value added can be determined accurately without unreasonable difficulty. If the merchandise maintains its identity but forms a minor element of the merchandise sold in the United States, the method is unjustified.
Who Actually Ends Up Carrying the Duty
Valuation is where the duty number is set, but liability is a separate question, and the answer is unforgiving. 19 CFR 141.1 states that duties and the liability for their payment accrue upon imported merchandise on arrival of the importing vessel within a Customs port with the intent then and there to unlade, or at the time of arrival within the customs territory of the United States if the merchandise arrives otherwise than by vessel, unless otherwise specially provided for by law.
The liability for duties, both regular and additional, attaching on importation, constitutes a personal debt due from the importer to the United States which can be discharged only by payment in full of all duties legally accruing, unless relieved by law or regulation. Payment to a broker covering duties does not relieve the importer of liability if the duties are not paid by the broker. The liability may be enforced notwithstanding the fact that an erroneous construction of law or regulation may have enabled the importer to pass his goods through the customhouse without payment. And delivery of a Customs bond with an entry is solely to protect the revenue of the United States and does not relieve the importer of liabilities incurred from the importation of merchandise into the United States.
Two practical consequences follow. First, the importer, not the factory and not the freight forwarder, is the party on the hook. Where an agent handles customs clearance, the importer needs a clear understanding of the declaration the agent is making, because the declaration is made in the importer’s name. Second, the liability also constitutes a lien upon the imported merchandise, which may be enforced while the goods are in the custody or subject to the control of the United States, and the claim of the government for unpaid duties against the estate of a deceased or insolvent importer has priority over obligations to creditors other than the United States.
Country of origin marking requirements run in parallel with all of this, because an entry that declares the wrong origin creates a valuation problem of a different kind. Our guide to country of origin marking for metal goods covers the marking rules that apply to imported souvenirs.
Building the Valuation File Before the Container Is Booked
None of the above requires a customs lawyer for an ordinary commercial order. It requires a small set of documents, collected at the time the order is placed, and a decision about who owns the tooling.
Before the purchase order is signed, agree in writing who funds the mold, what its value is, and over how many units that value is amortized. Keep the mold invoice or the production cost record. If the design is prepared outside the United States, record where the work physically happened, and if a United States-based designer is involved, record their role. Note in the packing instruction which materials are customer-supplied, because their cost is an addition to the price. Read the licence terms in the purchase agreement and the licence agreement together and establish whether the fee is a condition of the export sale. If any part of the price is deferred until the goods sell, convert that to a fixed number before shipment. And record the delivery terms, because they determine whether freight sits inside or outside the price.
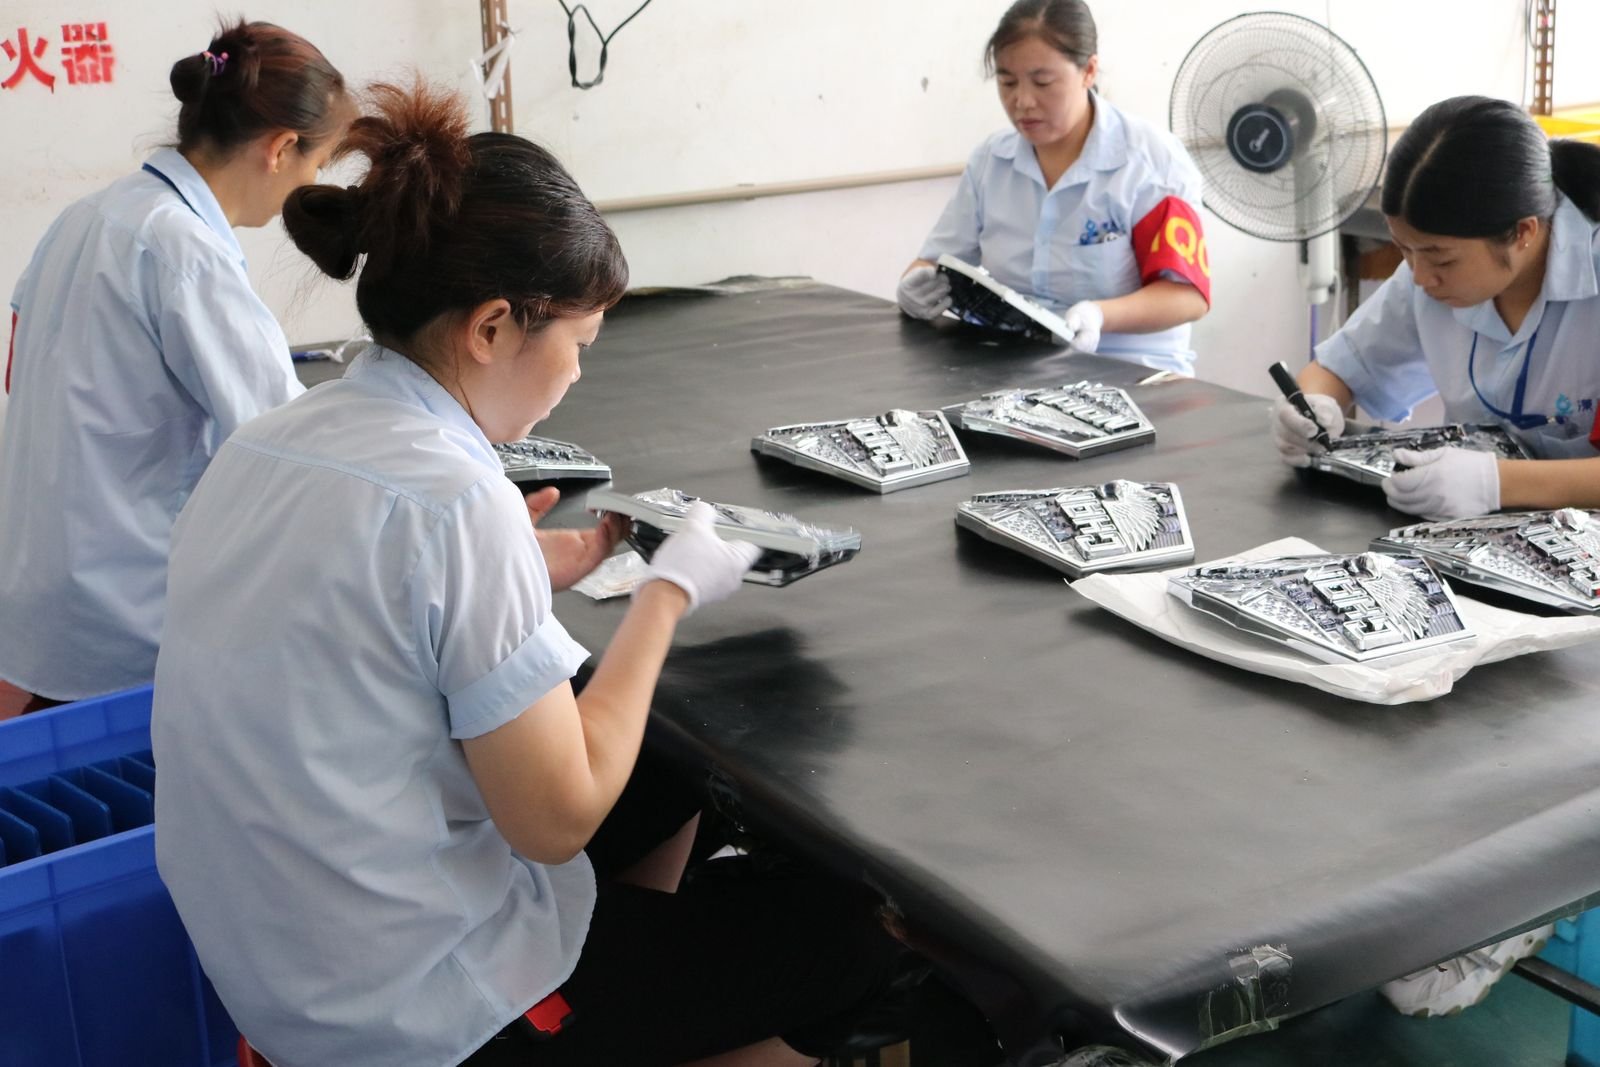
For buyers working with a factory that has been making goods for you for a while, the practical problem is that the mold was set up years ago and nobody wrote down what it cost or how it was amortized. That is the moment to fix it rather than to discover it at audit. A factory that keeps tooling records and can produce the cost basis for a mold is worth more than one that quotes a low unit price and cannot document the tooling. Our production setup runs on zinc alloy die casting as the main process, with stainless steel, brass and bronze and iron also available, across gold, silver, rose gold, antique brass, antique silver, antique copper, black nickel and dual tone plating finishes. Minimum order quantities are 100 pieces against an existing mold, 500 pieces for a standard design using an existing mold, and 1,000 pieces for most fully custom die casting, with sampling in seven days and production in fifteen to twenty days. Tooling cost, amortization schedules and any maintenance charge are quoted on request against a specific programme.
One closing point about evidence. The regulation states that additions to the price actually paid or payable are made only if there is sufficient information to establish the accuracy of the additions and the extent to which they are not included in the price. That is the test a piece of documentation has to pass: not whether it exists, but whether it establishes the number and whether that number is already on the invoice. A packing list that shows boxes but not the cost of the foam does not establish the packing addition. An invoice for the mold at a lump-sum price with no allocation does not establish an apportionment. Building the file properly takes less effort than reconstructing it.
The International Framework Behind National Rules
United States rules are one implementation of an international agreement, and buyers who import into other markets will meet the same logic in different language. The Agreement on Implementation of Article VII of GATT 1994 is the agreed legal text. Its General Introductory Commentary explains the architecture directly: the primary basis for customs value is transaction value as defined in Article 1, Article 1 is to be read together with Article 8, and Articles 2 through 7 provide methods of determining the customs value whenever it cannot be determined under the provisions of Article 1.
Article 1 sets the customs value of imported goods as the transaction value, that is the price actually paid or payable for the goods when sold for export to the country of importation, adjusted in accordance with Article 8, provided four things. That there are no restrictions as to the disposition or use of the goods by the buyer other than restrictions imposed or required by law or by the public authorities in the country of importation, restrictions limiting the geographical area in which the goods may be resold, or restrictions that do not substantially affect the value of the goods. That the sale or price is not subject to some condition or consideration for which a value cannot be determined with respect to the goods being valued. That no part of the proceeds of any subsequent resale, disposal or use of the goods by the buyer will accrue directly or indirectly to the seller, unless an appropriate adjustment can be made under Article 8. And that the buyer and seller are not related, or where they are related, that the transaction value is acceptable under paragraph 2.
Article 8 is the mirror image of the United States rules and uses almost the same vocabulary. Additions are made for commissions and brokerage except buying commissions, for the cost of containers treated as being one for customs purposes with the goods, for the cost of packing whether for labour or materials, for the value apportioned as appropriate of goods and services supplied directly or indirectly by the buyer free of charge or at reduced cost for use in connection with the production and sale for export of the imported goods, and within that group the same four categories of materials and components, tools, dies and moulds, materials consumed in production, and engineering, development, artwork, design work, plans and sketches undertaken elsewhere than in the country of importation. Additions are also made for royalties and licence fees related to the goods being valued that the buyer must pay, directly or indirectly, as a condition of sale, and for the value of any part of the proceeds of any subsequent resale, disposal or use that accrues directly or indirectly to the seller.
Two provisions in Article 8 are worth memorising because they are the international form of the same trap. Additions to the price actually paid or payable are made under Article 8 only on the basis of objective and quantifiable data. And no additions are made in determining the customs value except as provided in that Article. The list is closed, the evidence standard is objective and quantifiable, and a buyer who cannot quantify an addition is not permitted to leave it out and hope.
Valuation Addition Responsibility Matrix
The table below is the working document to keep for a specific metal souvenir programme. It assigns each addition to the party that has to produce the evidence, states whether it enters the declared value, and names the document that makes it defensible. Work down it before the purchase order is signed, not after the entry is filed.
| Addition category | Who supplies it | Enters transaction value | Document that makes it defensible | Who signs for it |
|---|---|---|---|---|
| Buyer-funded die casting mold or stamping die | Buyer funds or funds at reduced cost; factory manufactures it | Yes, apportioned over the units the buyer elects | Mold invoice or production cost record plus a written amortization basis | Buyer approves the amortization basis in the purchase agreement before the first shipment |
| Artwork and design work prepared outside the United States | Buyer’s design studio or agent outside the US | Yes | Design fee invoice identifying where the work was performed | Buyer confirms the place of performance in writing |
| Artwork prepared inside the United States | Individual domiciled in the US acting as employee or agent of the buyer | No | Designer engagement, residence status, and link to the US-side engineering scope | Buyer’s design lead confirms the exception applies |
| Customer-supplied components or production consumables | Buyer ships parts to the factory or supplies consumables | Yes | Goods issue notes or shipping documents showing value and destination | Buyer keeps the issue record and passes a copy with the shipment file |
| Customer-supplied packing materials | Buyer supplies inner boxes, foam, printed inserts | Yes, as packing costs | Packing list separating containers from packing labour and materials | Factory issues a packing list that shows the split |
| Selling commission in the country of export | Factory’s sales agent | Yes, if not already in the invoice price | Agency agreement and commission statement | Factory discloses whether commission is embedded in the price |
| Licence or royalty paid as a condition of the export sale | Buyer pays a third party or the seller | Yes | Licence agreement showing the payment is a condition of the export sale | Buyer’s legal reviewer signs the payment structure |
| Licence or royalty for trademark or copyright use in the destination market | Buyer pays a third party | Generally no, when it is a selling expense of the buyer rather than a condition of the export sale | Licence agreement and confirmation that the payment is not a condition of the sale | Buyer records the basis for the treatment in the entry file |
| Deferred payment tied to resale in the destination market | Buyer pays the seller after sell-through | Yes, at the full amount, if the resale price can be determined in a reasonable period | Sales reporting and remittance records | Buyer converts this to a fixed price before shipment wherever possible |
| International freight and insurance | Carrier, depending on delivery terms | No, where excluded from the price; included only where the price is not an ex-factory price | Incoterm used on the order and the freight invoice | Buyer checks the delivery term against the invoice price before booking |
| Post-importation assembly, maintenance or technical assistance | Buyer’s own operation in the destination market | No | Cost breakdown identifying the post-importation work | Buyer’s controller separates these costs in the purchase order |
Two rows deserve attention because they are the ones most often got wrong. The tooling row is where the largest number usually sits, and the row is only as good as the amortization basis written down before the first shipment. The deferred payment row is the one that can take the whole transaction value away, because if the resale price cannot be determined in a reasonable period the transaction value cannot be determined at all.
Valuation is not a piece of paperwork that gets filed at the border. It is a set of decisions about who owns the tooling, who paid the design fee, how the packing was arranged and what the licence terms actually say, taken while the order is still being negotiated. Take those decisions deliberately and the declared value becomes arithmetic. Leave them to the last minute and it becomes a negotiation with an auditor. For quotations on tooling, sampling and production scheduling for a specific souvenir programme, contact Kingtop Metal Product at sales@kingtopgift.com.